The most expensive surprise in an HSBC personal loan can hide on the offer page, where prepayment penalties or insurance product requirements sit right beside the interest rate you were excited about.
Approval is the middle of the process. The total cost of borrowing printed in that offer is the real price tag, and you only see it after the credit check.
This guide is for salaried HSBC customers taking out a first personal loan and assuming their account turns it into a formality. The application can be smooth, but the contract deserves slower eyes.
How Do You Apply for an HSBC Personal Loan in 2026?
Applying for an HSBC personal loan takes six steps: compare the loan options, estimate repayments, submit the application, wait for the credit assessment, accept the offer, and collect the funds.
Applications go in online, by phone, or at a branch, and HSBC's secure portal lets you upload scanned documents in most regions.
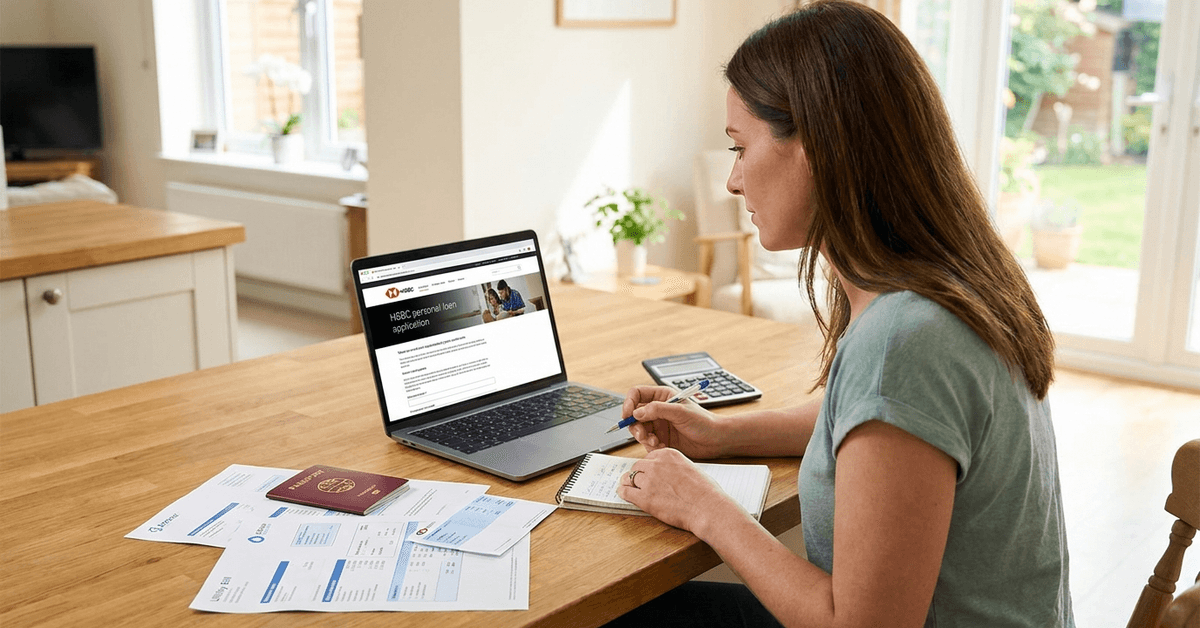
I'd call the fast-approval promise fair for tidy files, since online applicants typically hear back within a few working days. Inconsistent paperwork or extra verification checks are what stretch the wait.
Who Can Get an HSBC Personal Loan, and What Paperwork Do You Need?
Salaried and self-employed applicants who meet HSBC's minimum age and income thresholds can apply, provided they show a reasonable credit rating and a clear ability to repay.
An HSBC personal loan is unsecured, so collateral is generally not required, but approval depends on your credit profile and income stability.
Rules differ by region, so check the current criteria on the official HSBC website for your country before filling anything in.
The Documents HSBC Usually Asks For
Expect to supply proof of identity such as a passport or ID card, proof of address like a utility bill, and proof of income through recent payslips or tax returns.
HSBC sometimes requests an employment letter or bank statements to confirm your income is consistent. Scanning everything into one folder now saves a panicked hunt for last month's payslip later.
Does Already Banking With HSBC Make Approval Easier?
Existing account holders can get a smoother review, and a well-established relationship with HSBC sometimes cuts the paperwork to a minimum.
Some customers also qualify for preferential rates or quicker digital applications. Non-customers are still considered, so an HSBC account is helpful but optional.
What Happens After You Submit an HSBC Loan Application?
After submission, HSBC runs a formal credit assessment that reviews your credit score, income details, and existing debts. This review can take a few days to complete.
Why the HSBC Loan Calculator Number Can Change
HSBC's loan calculators estimate monthly repayments, but the real offer depends on the formal credit assessment, so the number on screen stays an estimate.
I'd run HSBC's calculator backwards: start with the monthly payment your budget can carry, then shrink the loan amount until the estimate fits under it.
Starting from the maximum loan amount tends to anchor you to a bigger debt than the project needs, and bigger debt means a bigger total cost of borrowing.
What Slows Down the HSBC Credit Check?
HSBC may call applicants for clarification during the review, and these are the situations that tend to trigger a call or extra checks:
- Documents that look inconsistent, such as an income figure that doesn't match your payslips
- Incomplete paperwork or missing pages in scanned files
- Existing debts left off the application form
- Errors on your credit report that you never disputed
Checking your credit report first and fixing errors also helps on price, since a higher score can sometimes improve the rate HSBC offers.
How to Read Your HSBC Loan Offer Before You Accept It
Read the offer slowly, because the moment you accept it HSBC transfers the funds, often straight into your nominated account. An HSBC loan offer states the interest rate, the repayment term, and the total cost of borrowing, along with any prepayment penalties or insurance requirements tied to the loan.
Four lines on that offer page deserve a second read and, if anything feels vague, a direct question to HSBC:
- The total cost of borrowing, compared against the rate you saw advertised
- Any early repayment fee and how it gets calculated
- Any insurance product the loan requires you to buy
- Confirmation that a promotional rate covers your specific product and region
Fixed or Variable Rate on an HSBC Personal Loan?
HSBC may offer both fixed and variable rate personal loans, depending on where you live. A fixed rate keeps the monthly payment predictable, while a variable rate can move after you sign.
Branch representatives can clarify ambiguous terms, though their answers can feel cautious or generic. Ask for the answer in writing if a point affects your monthly budget.
Reading the contract aloud sounds like advice from a cautious grandparent. It still catches clauses your eyes slid past the first time.
Why I Wouldn't Rush to Pay Off an HSBC Loan Early
Paying off debt early is the advice everyone repeats, and I think it is wrong as a default for an HSBC personal loan until you've read the prepayment clause in your Step 5 offer.
Early repayment is possible on most HSBC personal loans, but fees may apply. If the fee swallows most of the interest you'd save, early payoff just hands HSBC the money in a different envelope.
So plan your exit before your entry. If you expect a bonus or windfall that could clear the debt within months, ask HSBC for the exact fee figure before you accept.
HSBC Customer, New Applicant, or Expat: Does the Process Change?
Yes, it shifts with your residency and banking history. Expatriates can apply for an HSBC personal loan in many locations, though extra documents or higher minimum income thresholds may apply.
| Applicant type | Can apply? | What to expect |
|---|---|---|
| Existing HSBC customer | Yes | Smoother review, possibly minimal paperwork and preferential rates |
| New HSBC customer | Yes | Standard identity, address, and income documents |
| Expat without permanent residency | In many locations | Additional documents and possibly higher income thresholds |
The less HSBC already knows about you, the more paperwork you should have scanned and ready on day one.
Is HSBC the Best Place for Your Personal Loan, or Should You Compare?
Compare before you commit: HSBC is one of several personal loan options alongside major banks, digital lenders, and local credit unions, and some of them may offer lower rates or fewer fees.
Reviewing two or three banks' terms side by side is a reasonable benchmark, and comparison sites such as Money Saving Expert can help you weigh the pros and cons.
When Sticking With HSBC Makes Sense
Staying with HSBC can make sense if you already hold an account there and your offer includes preferential rates or a quicker digital application.
I'd still set that offer beside two other lenders, since HSBC's promotional rates may only apply to certain products or regions.
Mistakes That Make an HSBC Loan Application Harder
These avoidable habits can turn a quick HSBC loan decision into a slow or disappointing one:
- Hiding existing debts or overstating income, which rarely survives the credit check
- Skipping a credit report review, then losing time to an error you could have fixed
- Signing without asking about insurance requirements or early repayment fees
- Leaving documents as paper copies until the day you apply
Questions People Ask About HSBC Personal Loans
A few questions come up again and again once people start an HSBC application, so the short answers sit below.
- Q: Do I need an HSBC account to get an HSBC personal loan?
No, non-customers are considered too. Existing account holders may simply get a smoother review and, in some regions, preferential rates worth comparing against your current bank. - Q: Is an HSBC personal loan secured against my house or car?
HSBC personal loans are generally unsecured, so you don't pledge collateral. The trade-off is that your credit profile and income stability carry the full weight of the decision. - Q: How fast will the money reach my account after approval?
Once you accept the offer, HSBC transfers the funds, often directly into your nominated account. Timing varies, and outstanding checks or post-approval requirements can hold the transfer up. - Q: Can I get an HSBC personal loan with a low credit score?
HSBC's eligibility rules can be strict on credit score and minimum income, so a weak score may mean denial or a higher rate. Fixing credit report errors first is the cheapest fix available. - Q: Can I ask HSBC to explain a loan term I don't understand?
Yes, HSBC representatives can clarify terms by phone or at a branch. Their answers can sound cautious, so keep asking follow-up questions until you could explain the clause to a friend.
Conclusion
An HSBC personal loan application is usually the easy part, especially when your documents are scanned and consistent. The offer page decides what you pay, so read the total cost of borrowing before the rate.
Check the early repayment fee and any insurance requirement, then compare HSBC against two other lenders. Run the calculator backwards tonight, and you may find you need a smaller loan than you planned.